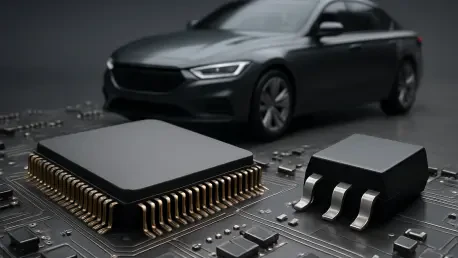
Specialized firms like Telechips and Nextchip are focusing on high-growth niches such as in-vehicle infotainment and advanced image recognition for driver assistance systems. This strategic pivot marks a significant moment in South Korea’s industrial history, as the nation moves to diversify its semiconductor prowess beyond the traditional dominance of memory chips. The “K On-Device AI Semiconductor Cooperation Forum” has recently highlighted the critical nature of this transition, positioning automotive AI chips as the primary engine for future mobility. By fostering a domestic ecosystem, the country aims to protect its automotive sector from the unpredictable fluctuations of the global supply chain. This is not merely a response to international competition but a calculated effort to integrate high-performance logic and artificial intelligence into the core of the local manufacturing economy. As vehicles transform into mobile data centers, the necessity of securing proprietary semiconductor technology becomes a matter of long-term economic sovereignty and industrial stability.
Market Evolution: Technical Complexity and Economic Growth
The financial prospects for the automotive semiconductor sector are immense, with the global market value projected to reach approximately $133 billion by 2030. This growth is driven by an 11.4% compound annual growth rate, reflecting the rapid transition of the automotive industry toward electrification and higher levels of autonomy. Specifically, segments dedicated to Advanced Driver Assistance Systems and autonomous driving are expanding at an even faster clip, often exceeding 15.6% annually. For South Korea, these figures represent more than just market statistics; they are a roadmap for economic resilience. By moving into these high-growth niches, the nation can balance the inherent cyclicality of its memory chip business with the steady, long-term demand of the automotive sector. This shift ensures that as cars become more sophisticated, the high-value components required to power them are designed and manufactured within the domestic industrial framework, capturing a larger share of the global tech value chain.
As vehicles evolve into sophisticated software-defined platforms, the sheer volume of silicon required to operate them is increasing at an unprecedented rate. Industry data suggests that the average value of semiconductors per vehicle is set to double over the coming decade, rising from approximately $860 to nearly $1,902 by the mid-2030s. This surge is fueled by the demand for complex information processing, high-speed connectivity, and efficient power management in electric drivetrains. Every new feature, from surround-view monitoring to predictive battery management, requires specialized logic chips that can handle intense computational workloads while maintaining extreme energy efficiency. For South Korea, this trend provides a unique opportunity to leverage its existing electronics expertise to create a new generation of automotive-grade processors. By focusing on the high-value segments of the mobility market, domestic firms are positioning themselves to become indispensable partners for global automakers who are increasingly reliant on advanced semiconductor architecture.
Strategic Integration: Overcoming Barriers for Technological Sovereignty
The current market disparity presents a significant hurdle, as South Korea’s share of the global automotive chip sector remains relatively small compared to established European and American giants. To overcome the strict safety standards and the rigorous “track record” requirements of the automotive industry, domestic firms are adopting a unified “joint development” model. This approach creates a synchronized pipeline where automakers and parts suppliers define technical requirements early, allowing fabless firms to design chips that are guaranteed a first customer. By manufacturing these components in domestic foundries like DB HiTek or SK keyfoundry, the industry ensures a closed-loop ecosystem that validates new technologies in real-world conditions. This collaborative strategy effectively bypasses the traditional barriers to entry by providing the necessary mass-production history required for global competition. It transforms the local supply chain into a resilient network capable of producing advanced power management and infotainment systems that rival international standards.
The strategic transition to a domestic automotive semiconductor ecosystem successfully laid the groundwork for technological sovereignty while shielding the local economy from global supply chain shocks. By integrating proprietary intellectual property with advanced manufacturing processes, the industry ensured that core mobility technologies remained under national control. This progress extended beyond the automotive sector, as the high-performance power modules and AI processing units developed for vehicles were eventually adapted for use in humanoid robotics and high-efficiency energy storage systems. Moving forward, stakeholders prioritized the standardization of security protocols to protect autonomous networks from emerging cyber threats, ensuring that future mobility remained both safe and reliable. These efforts demonstrated that a targeted, collaborative industrial policy could effectively bridge the gap between established global leaders and rising domestic innovators. Ultimately, the focus on automotive silicon transformed the nation’s high-tech landscape, securing its position as a dominant force in the global race for future mobility.