The global pharmaceutical landscape is currently navigating a period where the ability to manufacture highly specialized therapies rapidly has become more critical than the sheer volume of production itself, forcing a total reimagining of traditional outsourcing relationships. This roundup examines the strategic shifts occurring within the contract development and manufacturing organization (CDMO) sector as it moves past the reactive phase of previous years toward a model defined by precision, agility, and regional resilience. By aggregating insights from market analysts and industry leaders, this discussion clarifies how the industry is preparing for a new era of complex modality dominance and geopolitical restructuring.
Navigating the Strategic Pivot in Pharmaceutical Outsourcing
The global CDMO sector has entered a significant period of post-pandemic recalibration, transitioning away from the emergency-driven volatility toward a steady phase of specialized expansion. Observers note that the massive capacity once reserved for rapid vaccine deployment has been repurposed to address a burgeoning pipeline of long-term therapeutic innovations. This shift represents a maturation of the market, where sustainable growth is driven by technical sophistication rather than temporary surges in demand.
Strategic partnering now serves as the backbone of modern drug development, especially as the complexity of drug substances necessitates advanced manufacturing agility. Organizations are increasingly relying on contract partners to manage the technical risks associated with novel delivery systems and intricate molecular structures. The necessity of these partnerships is fueled by the reality that few pharmaceutical companies can maintain the internal infrastructure required to produce every modality in their increasingly diverse portfolios.
The road ahead suggests a period of intense focus on therapeutic specialization and the geographical realignment of production hubs. While clinical manufacturing experienced a brief lull as the market adjusted to new economic realities, a recovery is now visible as supply chains are restructured for greater security. This trajectory points toward a more stable environment where the success of a CDMO is measured by its ability to integrate into the client’s long-term strategic planning rather than providing simple overflow capacity.
The Surge of Complex Modalities and Commercial Resiliency
High-Growth Engines: Peptides, ADCs, and the Oligonucleotide Boom
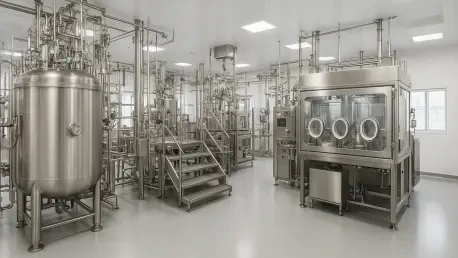
The pharmaceutical industry has moved decisively beyond small molecules, triggering a transition where complex therapies like Antibody-Drug Conjugates (ADCs) have reached mainstream commercial scaling. Analysts point to the massive investment in bioconjugation facilities as evidence that these high-potency treatments are no longer niche products. The ability to handle cytotoxic materials while maintaining sterile environments has become a primary differentiator for top-tier manufacturing partners.
Market data indicates a multi-billion dollar opportunity in the oligonucleotide space, with a projected compound annual growth rate of over 20 percent from 2026 to 2029. This explosive growth is largely driven by the shift toward precision medicine and the increasing use of RNA-based therapies for chronic conditions. As these treatments move from rare disease applications to broader indications, the demand for large-scale synthetic capacity is outstripping current supply, leading to significant capital expenditures across the sector.
Infrastructure constraints remain a primary concern, particularly regarding the high-volume demand for sterile fill-finish operations. The rise of GLP-1 agonists for diabetes and obesity has consumed vast amounts of injectable capacity, creating bottlenecks that impact other therapeutic areas like oncology. This scarcity has forced many drug developers to secure manufacturing slots years in advance, emphasizing the critical value of possessing “ready-to-use” sterile capacity in the current market.
Integrated Service Models: The Rise of End-to-End Manufacturing Ecosystems
Supply chain streamlining has led to the adoption of “one-roof” manufacturing strategies, where a single partner manages everything from drug substance production to final packaging. Leading organizations are promoting these integrated models to reduce the logistical friction and multi-vendor risks that often delay product launches. By centralizing the production process, companies can ensure tighter quality control and more seamless data transitions between different stages of the development lifecycle.
Strategic mergers and acquisitions have acted as a major growth catalyst, particularly those aimed at securing large-scale mammalian drug substance capacity. For instance, the acquisition of massive facilities, such as the site in Vacaville, illustrates a trend toward purchasing established, high-capacity infrastructure to meet the needs of the biologics market. These moves allow CDMOs to bypass the lengthy timelines associated with greenfield construction, providing immediate scale to their global clients.
The debate between localization and globalization has reached a new equilibrium as firms evaluate the competitive advantages of a diversified footprint. While global scale remains essential for cost-efficiency, possessing localized “on-shore” assets provides a layer of security against trade disruptions and regulatory changes. This balanced approach allows pharmaceutical companies to maintain a presence in cost-effective regions while ensuring that critical supplies are produced close to their primary consumer markets.
The Clinical Manufacturing Recovery: Quality Over Quantity
The investment landscape for clinical manufacturing has become increasingly discerning, with a clear shift toward “quality science” and data-backed biotech funding. Unlike the era of broad-based capital infusion, current investors are prioritizing programs with strong clinical evidence and a clear path to commercialization. This more disciplined approach is reshaping early-stage pipelines, favoring therapeutic candidates that offer significant clinical advantages over existing treatments.
Despite an uptick in biotech funding, there has been a delayed volume effect where increased capital has not yet fully translated into a surge of clinical manufacturing orders. Experts suggest this is due to the rigorous validation processes now required by investors before a project moves into the manufacturing phase. This temporary gap is expected to close as the current wave of well-funded programs progresses through the necessary regulatory hurdles and reaches the production stage.
Long-term pipeline health is now viewed through the lens of commercial viability rather than sheer numbers. Some market observers argue that the lower volume of clinical trials is actually a positive indicator, as it suggests the industry is weeding out weak candidates earlier in the cycle. This shift ensures that the projects reaching CDMOs are more likely to succeed, ultimately leading to a more robust and predictable commercial manufacturing environment in the coming years.
Geopolitical Realignments and the “China Plus One” Framework
De-risking has become a central theme in global sourcing decisions, influenced heavily by legislative actions like the BIOSECURE Act and the potential for shifting trade tariffs. Western pharmaceutical firms are actively evaluating their dependence on specific regions to ensure that political tensions do not disrupt the delivery of life-saving medicines. This movement has led to a systematic review of supply chains, with many companies seeking to diversify their manufacturing bases across multiple jurisdictions.
Despite these political headwinds, the persistence of Asian hubs remains a reality due to the massive price disparities and technical scale they offer. China continues to be a dominant force in the global market because Western sites often struggle to match the sheer speed and cost-effectiveness of Chinese operations. Consequently, many firms are not leaving these regions entirely but are instead adopting a strategy that maintains existing ties while adding backup capacity elsewhere.
India has emerged as the primary beneficiary of this fragmentation, particularly in the realm of cost-effective, export-oriented small-molecule manufacturing. The country’s ascendance is fueled by a mature regulatory environment and a massive workforce of highly skilled scientists. As companies look for alternatives to traditional hubs, the Indian market provides a unique combination of scale and affordability that is difficult to replicate in high-cost Western environments.
Strategic Imperatives for CDMO Resilience and Expansion
Securing a competitive edge in the current environment requires a commitment to prioritizing specialized capacity in high-demand segments. Investing in sterile injectables and complex biologics is no longer optional for organizations that wish to remain relevant to major pharmaceutical clients. These segments carry high barriers to entry, including significant capital requirements and the need for specialized technical talent, which helps protect the margins of those who successfully navigate the complexities.
Adopting flexible sourcing strategies is essential for pharmaceutical companies that must balance cost-efficiency with localized security. The most successful firms are those that can pivot between various geographic hubs depending on the regulatory climate and market demand. This flexibility ensures that the supply chain remains resilient even in the face of unexpected geopolitical shifts or regional manufacturing disruptions.
Mastering technical complexity is the final frontier for CDMOs looking to evolve from simple service providers into true strategic partners. This involves developing the expertise to manage multi-step bioconjugation and advanced formulation techniques that are required for the next generation of medicines. Those who can demonstrate a mastery of these difficult processes will be best positioned to capture the high-value contracts that define the modern therapeutic landscape.
Conclusion: Engineering the Future of Global Medicine
The market reached a consensus that the convergence of technical innovation and geopolitical pragmatism defined the most successful strategies in the pharmaceutical outsourcing sector. It was observed that the fundamental demand for CDMO expertise remained stronger than ever, provided that organizations could adapt to the shifting needs of a more sophisticated client base. The transition toward complex modalities and integrated service models proved to be the most effective way to secure long-term commercial resiliency.
Moving forward, the industry should focus on standardizing the production of advanced therapies to bring down costs and increase patient access globally. Leaders must prioritize the development of modular manufacturing platforms that can be quickly scaled or relocated in response to changing trade policies. By embracing digital integration and automated quality systems, CDMOs will be able to provide the transparency and speed that modern drug developers require to stay competitive.
Ultimately, the ability to harmonize global scale with local agility became the hallmark of the industry’s leaders. The focus shifted toward creating a more interconnected and responsive manufacturing network that could withstand the pressures of a fragmented global economy. As the sector continues to evolve, scientific excellence and operational flexibility will remain the primary drivers of growth, ensuring that the next generation of medicines can be delivered to patients with unprecedented efficiency and reliability.