Premier’s EBITDA margin improved by 120 basis points to 13.9%, reflecting the realization of significant merger synergies in procurement and distribution. This performance serves as a testament to the group’s ability to absorb the Rhodes Food Group (RFG) assets into its existing operational framework without losing momentum. The integration of brands such as Rhodes Quality and Bull Brand has not only expanded the company’s market footprint but also fortified its earnings base against broader economic volatility. Revenue increased significantly by 38.8%, climbing to R14.3 billion, while the headline earnings per share rose by 27.1% to reach 711 cents. This financial growth occurred while the company maintained a disciplined approach to its balance sheet, keeping a leverage ratio of 0.7x despite the substantial debt required for the acquisition. The expansion reflects a robust strategy of modernization and fiscal responsibility that has reshaped the group’s corporate profile.
Operational Synergy and Divisional Performance
Operational performance across the group’s various segments has been defined by a focus on integration and the extraction of value from newly acquired manufacturing assets. This period has seen the successful deployment of a unified corporate strategy that prioritizes efficiency and cost leadership, particularly within the food production segments. By centralizing core functions like procurement and distribution, the organization has created a more cohesive structure that can respond dynamically to market shifts. The focus has not only been on cost-cutting but also on enhancing the output quality and consistency across all brands, ensuring that the legacy Premier products and the new RFG additions share the same high standards. This phase of the group’s development marks a departure from purely organic growth, signaling a more aggressive stance in the regional consumer goods market. The synergy between different production hubs is now being used to drive a more sustainable operation.
Optimizing the Core Manufacturing Footprint
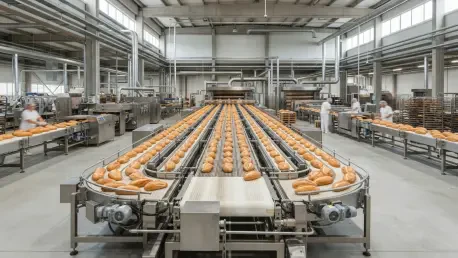
The Millbake division remains the central engine of the group’s profitability, thriving under a rigorous “low-cost producer” strategy that prioritizes infrastructure modernization. Recent investments include the Aeroton bakery reaching full-scale production and the commissioning of a new facility in Middelburg to optimize the supply chain. To further streamline costs, the company shuttered older, less efficient sites, ensuring that its core bread and flour operations remain lean and highly competitive. This focus on physical assets allows for a more responsive supply chain capable of handling high volumes while keeping production costs at a minimum. The transition from older facilities in Potchefstroom and Hermanstad to modern, high-tech bakeries ensures that the group can maintain its market share in the staple food sector. By focusing on efficiency, the division managed a 23.7% increase in EBITDA contribution despite a modest 1.3% growth in revenue for that specific segment.
Integration of the Culinary Segment
With the successful inclusion of the culinary business, the group’s revenue composition has undergone a fundamental shift, reducing its reliance on traditional Millbake sales. This new segment, bolstered by strong performance in fresh pastries and a key partnership with Woolworths, is already yielding significant merger synergies in procurement and distribution. Management anticipates even greater gains as the division fully migrates to the group’s unified supply chain and merchandising platforms over the coming months. The culinary division now represents a significant portion of total group sales, moving the contribution of the Millbake sector from 81% to a more balanced 66%. This diversification is critical for mitigating the risks associated with volatile grain prices and changing consumer habits in the staple foods market. The fresh range, particularly the high-demand pie and pastry category, has emerged as a high-margin growth driver that complements the group’s long-standing dominance in dry goods.
Strategic Navigations and Future Projections
Strategic navigation in a fluctuating economic environment requires a delicate balance between defensive measures and aggressive capital deployment. The group has adopted a proactive approach to portfolio management, identifying areas of potential weakness early and implementing corrective measures to safeguard profitability. This oversight extends beyond simple financial monitoring to include a deep analysis of consumer behavior and global market trends that might affect long-term viability. By maintaining a lean operational structure and a strong focus on cash generation, the firm has preserved its ability to invest in high-growth opportunities even while addressing localized market challenges. The following sections explore how the company has managed these external pressures while continuing to allocate capital in a way that maximizes shareholder value and ensures organizational longevity. This strategic foresight has allowed the group to remain resilient in varying macroeconomic conditions.
Addressing Market Headwinds: Consumer Trends and Portfolio Adjustments
Despite the overall upward trajectory, the group is proactively addressing headwinds in the personal care and sugar confectionery sectors where consumer constraints have dampened demand. In the personal care segment, formal retail channels have seen a noticeable shift as consumers grapple with financial pressures, often opting for lower-priced private-label alternatives. This trend has forced the group to reassess its pricing strategies and promotional efforts to maintain brand loyalty without sacrificing margins. Meanwhile, the sugar confectionery department has faced volume challenges that require corrective actions to stabilize its market position. These adjustments involve a mix of product innovation and targeted marketing to remind consumers of the value proposition offered by the group’s established brands. Even with these hurdles, the UK-based operations have provided a helpful counterbalance, showing growth in specific categories that have offset the sluggish performance in other segments.
Capital Allocation and Long-Term Stability
The successful integration of the RFG assets proved that the group was capable of executing large-scale acquisitions while simultaneously improving its internal efficiencies. Moving forward, the focus shifted toward maximizing the return on invested capital, which already saw an increase from 17.6% to 20.6% during the recent reporting cycle. Stakeholders were advised to monitor the progress of the unified merchandising platform, as its full implementation remained a key driver for margin expansion in the culinary sector. Additionally, the organization prioritized the exploration of new export markets to leverage its modernized manufacturing base. The transition into a more diversified food and personal care entity provided a solid foundation for future growth, allowing the firm to weather domestic economic shifts with greater resilience. This period of consolidation and strategic refinement established a new benchmark for excellence, ensuring that the company remained a dominant force throughout the decade.