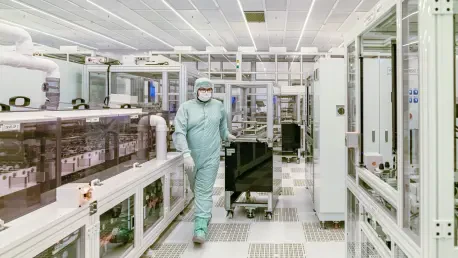
Data from UNCTAD suggests that the financial rewards of semiconductor technology are dictated by intellectual property ownership rather than the physical act of manufacturing. While the global race to subsidize domestic chip production has intensified, with nations committing staggering sums to build massive fabrication plants, the underlying economic structure remains heavily skewed. Current industrial trends indicate that the primary beneficiaries of this capital infusion are often the firms that control the blueprints and design algorithms, rather than the regions that host the physical infrastructure. As of 2026, the cost of establishing a leading-edge facility has reached tens of billions of dollars, yet the revenue generated by the actual pressing of silicon is only a fraction of the final market price. This fundamental disparity raises critical questions about whether taxpayers are truly seeing a return on their investment or if they are simply subsidizing the profit margins of multinational technology giants.
The Economic Imbalance of Global Semiconductor Production
The semiconductor value chain is a complex hierarchy where profit margins are distributed unevenly across different stages of production. While the world focused on the recent supply chain shortages that crippled automotive and consumer electronics markets, the financial data revealed a surprising reality about where the money actually flows. High-end computing systems, specifically those tailored for large-scale artificial intelligence training, serve as a perfect example of this phenomenon. In these elite ecosystems, the value added by the physical manufacturer is dwarfed by the value attributed to the companies that own the architectural design and software integration. Governments are effectively competing to host the most expensive and least profitable segment of the lifecycle, while the high-margin “brain work” remains concentrated in a few specific global hubs.
Value Distribution: Part 1. The Power of Intellectual Property
The internal economics of high-end AI server systems illustrate the massive gap between design and production. For instance, an analysis of the Nvidia GB200 NVL72 system, which carries an estimated market value of $3.3 million, shows that the company responsible for the design captures approximately 66.8% of the total value added. This revenue is tied directly to the intellectual property and the software stack that makes the hardware functional. In contrast, the manufacturing partner, such as Taiwan’s TSMC, which performs the incredibly delicate task of etching billions of transistors onto silicon, receives only about 5% of that value. This distribution confirms that even in the most advanced technological sectors, the physical factory is treated more like a high-precision service provider than a primary owner of the final product’s wealth.
Furthermore, this disparity extends to the distribution of wealth within the companies themselves. Across the entire semiconductor production chain, profit after tax accounts for nearly 68% of the total value generated, while corporation taxes contribute roughly 12.4%. The workforce, which is often the primary justification for state subsidies, receives only 14.2% of the value in the form of salaries and benefits. When narrowing the focus to the workers directly involved in the physical production of hardware, the number drops even further to a mere 4.2%. This suggests that while a new factory brings thousands of jobs to a region, the vast majority of the wealth created by those workers flows back to the corporate headquarters of the technology owners, leaving the local economy with a relatively small portion of the total economic gain.
Value Distribution: Part 2. The Global Subsidy Race and Market Inefficiency
The scale of state intervention in the semiconductor industry reached unprecedented levels within the last two years. Reports from the OECD documented over $100 billion in industrial subsidies across 525 large industrial groups, marking the highest level of state support since the financial crisis of 2008. While these funds are intended to secure domestic production, researchers warn that they do not always lead to improved efficiency or increased investment. In many cases, subsidies allow firms to gain market share without necessarily advancing their technological capabilities. This creates a risk where countries with limited budgets may find themselves overpaying to attract companies that are simply looking for the highest bidder, rather than the most innovative environment.
Moreover, there is a growing concern that these subsidies act as a form of compensation for underlying structural weaknesses. When a government offers multi-billion dollar grants to a chipmaker, it is often trying to offset high energy costs, a lack of skilled labor, or insufficient infrastructure. By choosing to direct capital toward corporate incentives instead of investing in education or power grids, states may be creating a fragile industrial base that remains dependent on continuous government support. If the subsidies were to disappear, the factory might no more be competitive on a global scale. This dynamic shifts the risk from the private corporation to the public sector, as taxpayers become the guarantors of an industry that may not be sustainable without ongoing state intervention.
Government Strategies and the Evolution of Industrial Support
As the limitations of traditional grant-based subsidies became clearer, governments began to refine their approaches to industrial policy. The shift from simply writing checks to becoming active participants in the semiconductor market reflects a growing realization that the old model was insufficient for capturing long-term value. Some nations have experienced the bitter reality of corporate strategy shifts that left planned projects in limbo, while others have pioneered new ways to ensure that the public receives a tangible piece of the corporate pie. This evolution in strategy is not just about bringing factories home; it is about finding a way to make those factories contribute to the national balance sheet in a more meaningful and secure way than just through basic payroll taxes.
Corporate Commitments: Part 1. The Fragility of Subsidized Expansion
The risks inherent in relying on corporate promises were vividly demonstrated by Germany’s experience with the American chip manufacturer Intel. In 2023, the German government moved forward with a plan to provide nearly €10 billion in aid for a massive production site in Magdeburg, a project with a total value exceeding €30 billion. Local and federal officials spent years planning for the creation of 3,000 permanent high-tech jobs, viewing the project as a cornerstone of the nation’s industrial future. However, as global market conditions shifted and corporate priorities changed, the project was unexpectedly halted in 2025. Although the German government did not lose the money, as the payments were conditional on construction, the nation lost years of strategic momentum and the prospect of an entire industrial ecosystem.
This incident highlighted the fundamental power imbalance between sovereign states and global tech giants. No matter how much a state is willing to pay, the final authority remains with corporate boards that must answer to shareholders and respond to fluctuating global demand. When a company decides to pull back on its investments, the host country is left with empty plots of land and a void in its industrial strategy. This vulnerability has forced many policymakers to rethink the “subsidy-first” approach. They have realized that the mere presence of a factory is not a guarantee of long-term stability, especially when the technology and the capital behind that factory can be redirected to other parts of the world with very little notice or recourse for the host nation.
Corporate Commitments: Part 2. The Transition to State Equity Ownership
In a significant departure from traditional industrial policy, the United States introduced a model that moves beyond simple grants and toward direct state equity. Under the frameworks established by the CHIPS Act, the American government negotiated a deal to take a 9.9% equity stake in Intel as part of an $8.9 billion aid package. This move effectively turned the federal government into a major shareholder, allowing the state to profit directly from the company’s future success and stock appreciation. By taking an ownership position, the government aims to ensure that taxpayers receive a direct financial return if the company performs well, rather than just relying on the indirect benefits of job creation and general economic activity.
However, this transition to state capitalism introduces a new set of complexities and potential conflicts of interest. As a major shareholder, the government now has a financial incentive to enact policies and regulatory decisions that specifically benefit the company it owns. This blurs the line between a neutral market regulator and a profit-motivated participant, potentially creating an uneven playing field for competitors who do not have the state as an investor. While the equity model provides a more direct way to capture the “lion’s share” of profits, it also risks distorting market competition and tying the government’s financial interests to the success of a single corporate entity. This strategy represents a bold and controversial experiment in how modern states interact with the high-tech sector.
Strategic Security and the Future of Regional Sovereignty
Beyond the immediate financial returns, many nations view semiconductor subsidies through the lens of national security and industrial resilience. For these regions, the “profit” is not measured in currency, but in the ability to keep domestic industries running during times of global crisis. The memory of recent chip shortages, which halted production lines for everything from pickup trucks to medical devices, remains a powerful motivator for state intervention. While the chips produced in these subsidized factories might not be the most advanced or the most profitable, they are the essential components that prevent a total economic shutdown. This strategic logic has led to a focus on “legacy” technology, which, while less glamorous than high-end AI, is vital for the stability of a modern industrial economy.
Supply Resilience: Part 1. Insuring the Industrial Base
The European Union’s approach to semiconductor manufacturing, particularly through projects like the ESMC venture in Dresden, serves as a primary example of prioritizing security over sheer profitability. This project, a partnership between TSMC and European firms like Bosch and Infineon, was backed by €5 billion in German state aid. Rather than chasing the 3-nanometre chips used in the latest smartphones, the Dresden facility focuses on older nodes, such as 28-nanometre to 12-nanometre technology. These legacy chips are the workhorses of the automotive and industrial machinery sectors. For Europe, the value of this factory lies in its role as an insurance policy. By having a domestic source for these sensors and controllers, the European automotive industry can avoid the catastrophic supply chain disruptions that previously cost the region billions in lost production.
Despite the strategic benefits, the financial transparency of these deals often remains limited. While agreements like the one in Dresden include clauses for sharing “excess profits” with the state, the exact definitions of what constitutes a profit threshold are rarely disclosed to the public. Furthermore, the reliance on foreign technology partners means that even these “sovereign” factories are subject to the constraints of international licensing and control. The host country provides the land, the power, and the subsidies, but the ultimate control over the production process often remains in the hands of the foreign partner. This creates a situation where the region achieves supply security, but at the cost of long-term dependency on external technological expertise and the intellectual property of others.
Supply Resilience: Part 2. The Boundaries of Knowledge Transfer
A persistent challenge for nations hosting subsidized factories is the refusal of leading-edge firms to transfer their most valuable knowledge. Countries like Taiwan maintain strict policies ensuring that any manufacturing facility built abroad must use technology that is at least one generation behind what is available domestically. This “N-minus-one” policy ensures that the most sophisticated and profitable intellectual property remains within the borders of the originating country. Consequently, even when a nation spends billions to attract a top-tier manufacturer, it is effectively buying a version of the technology that is already on the path toward obsolescence. The high-value knowledge premium remains out of reach, leaving the host nation in a permanent state of technological catch-up.
This boundary on knowledge transfer underscores the reality that building a factory is not the same as building an industry. A factory is a physical asset that can be constructed with enough capital, but an industry is built on a foundation of researchers, designers, and innovators who own the underlying science. States that provide the infrastructure and labor without developing the corresponding domestic design capabilities find themselves at the bottom of the value chain. They may enjoy the secondary benefits of local employment, but they remain excluded from the massive profits generated by the next generation of technological breakthroughs. This barrier is the single greatest obstacle to achieving true technological sovereignty through the use of state subsidies alone.
Redefining Success in the Next Era of Technology Policy
The landscape of semiconductor manufacturing underwent a profound transformation as nations realized that physical production was only one component of a much larger economic puzzle. In the preceding years, the consensus among global economists and policymakers shifted toward a more nuanced understanding of value capture. It was observed that the most successful regions were not necessarily those with the most factories, but those that fostered a comprehensive ecosystem of design and research. The lessons learned from the massive subsidy campaigns of the mid-2020s provided a clear roadmap for the future, emphasizing that long-term prosperity required a move away from simply funding the “where” of technology and toward investing in the “what” and the “how.”
Final Analysis: Part 1. Learned Lessons in Value Capture
The historical analysis of state-funded chip factories demonstrated that the primary beneficiaries were consistently the entities that controlled the intellectual property and the high-level system architecture. Nations that focused solely on attracting physical manufacturing plants found that they were essentially providing low-cost infrastructure and labor to foreign giants, while the most significant financial gains were repatriated to corporate headquarters. The data proved that the manufacturing phase, while labor-intensive and essential, remained the least profitable part of the modern technology chain. This realization prompted a strategic pivot, as governments began to look for ways to move up the value chain by supporting domestic fabless design firms and advanced research institutions.
This shift in perspective was largely driven by the observation that jobs created in subsidized factories did not always lead to a broader distribution of wealth within the host community. Because the high-margin profits were largely retained by the technology owners, the local economic impact was often limited to service-sector growth and modest tax returns. The most successful examples of industrial policy were those that integrated manufacturing with local design and software development, creating a synergistic effect that kept more of the value added within the domestic economy. These regions proved that the true “lion’s share” of profit could only be captured by those who controlled the underlying knowledge and innovation, rather than just the physical assembly of the final product.
Final Analysis: Part 2. Recommendations for Sustainable Ecosystems
To ensure that future investments in technology yield more than just physical infrastructure, governments must transition toward a holistic ecosystem approach. This involves moving beyond the “subsidy race” and focusing on the development of specialized talent and domestic intellectual property. Instead of competing solely on the size of a grant, regions should invest in specialized education and research parks that encourage the growth of domestic design firms. By creating an environment where local engineers can design the chips that are produced in subsidized factories, a nation can capture both the manufacturing value and the much higher design value. This dual approach is the only way to ensure that the wealth generated by the semiconductor industry remains within the borders of the country that funded it.
Furthermore, future policy should prioritize strategic partnerships that include meaningful knowledge transfer and collaborative research. Any large-scale subsidy should be contingent upon the establishment of local research and development centers that are integrated with the host country’s university system. This ensures that the technological expertise brought in by foreign firms eventually permeates the local workforce, creating a self-sustaining cycle of innovation. By shifting the focus from being a provider of cheap labor and land to being a partner in the creation of new knowledge, states can move away from their role as secondary players in the global wealth chain. The ultimate goal is to build an industrial base that is defined not by the size of its factories, but by the depth of its intellectual capital.